A chart shows past prices. It does not prove that your trade could get each price. Prices move while an order waits. The price to buy may also differ from the price to sell. A useful backtest accounts for these costs.
Four costs that are easy to blend together
Trading cost is not one number. Separate each source so you can explain the assumption, change it, and see which part of the strategy is most sensitive.
Commissions
Commissions and explicit fees are usually the easiest costs to document. They may be charged per share, per contract, per order, or through another schedule. “Commission free” does not mean execution is frictionless; it only removes or changes one visible fee.
Bid-ask spread
A buyer often crosses toward the ask and a seller toward the bid. A test that always transacts at a midpoint or last-traded price can give the strategy a price that was not realistically available for the order being modeled.
Slippage
Slippage is the difference between an expected execution and the actual fill. It can result from fast price movement, order type, liquidity, delay, gaps, or queue position. It is not constant, so a single estimate should be treated as a scenario rather than a promise.
Market impact
Larger orders can consume available liquidity and influence the price. A test based on small historical bars may not reveal whether the proposed size could have traded without changing the market. Capacity is therefore part of the strategy specification, not an afterthought.
Why turnover changes the question
Small costs can become decisive when they repeat frequently. A slow strategy with a wide expected edge may react differently to friction than a high-turnover strategy whose average trade is small. Compare total modeled costs with gross strategy results, the average trade, and the frequency of entries and exits.
Do not conclude that a cost assumption is harmless merely because its per-trade value looks small. Ask how often it occurs and whether the strategy depends on very precise entry or exit prices.
If a modest cost estimate erases the result, the useful finding is fragility—not a reason to hide the estimate.
A worked cost-sensitivity example: 200 round trips
The following numbers are invented for arithmetic practice. They are not a TradeLab result, a live strategy, a broker fee schedule or a forecast. Hold a hypothetical trade list fixed: 200 completed round trips, exactly one entry fill and one exit fill per round trip, with a total gross result of $1,000 before the incremental costs shown here. That means 400 fills.
For this simplified exercise, the dollar assumption is an all-in incremental cost per fill, not per round trip, share or contract. The number of fills and gross result stay fixed so that only this cost assumption changes.
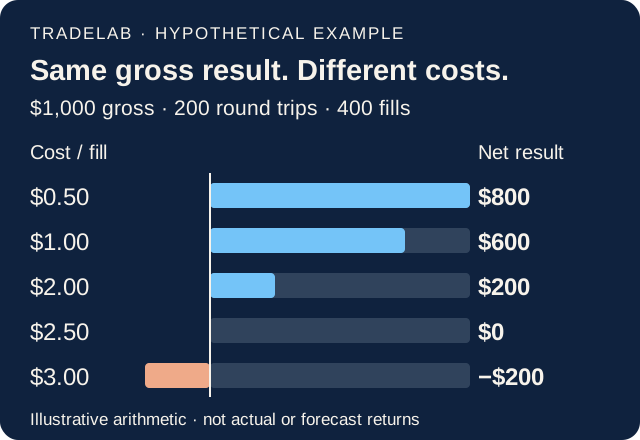
| Cost per fill | Total cost (400 × input) | Net ($1,000 − cost) |
|---|---|---|
| $0.50 | $200 | $800 |
| $1.00 | $400 | $600 |
| $2.00 | $800 | $200 |
| $2.50 | $1,000 | $0 |
| $3.00 | $1,200 | −$200 |
The break-even cost in this exercise is $1,000 ÷ 400 = $2.50 per fill, equivalent to $5 per completed round trip under the one-entry, one-exit assumption. Above that input, the fixed hypothetical gross result is smaller than the modeled total cost. This threshold describes these invented numbers only.
Check the units before reusing the calculation
- Count the charged events. A round trip normally includes entry and exit, but partial fills, scaling and different fee bases can change the count. A per-order fee cannot automatically be treated as a per-fill fee.
- Convert to one basis. Per-share or per-contract costs require quantity; percentage fees require transaction value. Keep the quantity, currency and event basis beside each input.
- Avoid double counting. If the simulated fill price already includes spread or slippage, do not subtract the same friction again as an extra cost.
- Rerun the actual model. This table holds the trade list fixed. In an execution simulation, different fills, available capital, position sizes or missed orders can also change the trades and gross result.
As one documented implementation, TradingView's strategy-properties documentation distinguishes percentage, per-contract and per-order commission settings, applies commissions at entry and exit, and expresses its slippage setting in ticks. Those are TradingView conventions, not a claim about TradeLab controls. Check the actual units and behavior of whichever research tool produced the test.
Use scenarios instead of one “correct” number
Historical execution cannot be reconstructed perfectly from bar data. Build at least three documented scenarios: a low-friction case, a central planning case, and a stressed case. The numbers should reflect the instrument, order type, timeframe, and expected size—not a generic value copied from another strategy.
- Start with explicit fees. Record the applicable commission and venue assumptions.
- Model the spread. State whether entries and exits transact at the bid, ask, midpoint, or another defensible convention.
- Add slippage scenarios. Test more than one value and explain what each scenario represents.
- Review turnover. Calculate how often the assumed friction is paid and which trades are most affected.
- Stress size and liquidity. Ask whether the historical volume and spread could plausibly support the order.
Match the cost model to the order logic
A market order, limit order, stop order, and next-bar execution do not share the same fill assumptions. Neither do a daily strategy and an intraday strategy. Write the order type, submission time, earliest possible fill, and behavior when the desired price is not available.
This timing work complements the look-ahead bias audit. A cost estimate cannot repair an impossible signal-to-fill timeline, and a valid timeline does not make a frictionless price realistic.
Inspect trades instead of trusting only totals
Review several individual trades under each cost scenario. Include ordinary trades, fast-moving periods, gaps, and the trades that contribute most to the result. Confirm that the assumed execution is consistent with the strategy rules and the data resolution.
Then repeat the broader backtest validation checklist after costs are applied. A strategy can pass the logic audit and still fail the economic test once realistic friction is included.
What a cost-adjusted test can tell you
It cannot predict the exact price of a future fill. It can show whether the conclusion survives a defensible range of execution assumptions, whether turnover consumes the modeled edge, and where the strategy needs more evidence.
Preserve the gross result, each cost input, the cost-adjusted result, and the scenario name together. That record makes later paper observation easier to compare without rewriting history.
Historical tests are hypothetical, depend on their data and assumptions, and do not predict future results. Actual commissions, spreads, slippage, liquidity, delays, and market impact can differ materially from a model. Paper trading also differs from live execution. This material is educational and is not financial advice or a recommendation to trade.